Behind at 50? New Data Reveals What Americans Actually Have Saved
Turning 50 often brings a sharper question than any birthday card: am I actually on track for retirement? A widely discussed thread on Reddit’s r/personalfinance, drawing on new survey numbers, has put that anxiety into perspective — showing how much Americans in their fifties really have saved, and how far the typical household is from the figures often quoted as necessary.
The short answer is that most people are behind the textbook benchmarks, but they are not alone, and 50 is not too late to change the trajectory. Understanding the real numbers, rather than the alarming headlines, is the first step.
What the Typical 50-Year-Old Actually Has
Data from the Federal Reserve’s Survey of Consumer Finances, summarised by outlets such as Investopedia, consistently shows a wide gap between average and median retirement savings. Averages are pulled upward by a small number of very wealthy households. The median — the household in the middle — tells a more honest story, and for Americans around 50 that median retirement account balance is far lower than the million-plus figures promoted in advertising.
Many households in their late forties and early fifties hold retirement savings in the low six figures or less, and a significant share have little or nothing saved in dedicated retirement accounts at all, even if they own a home or expect Social Security income. That context matters: feeling behind at 50 usually means being roughly typical, not uniquely careless.
Our coverage on TechKap regularly notes the same pattern in personal technology and finance — tools are more available than ever, from automatic payroll contributions to low-cost index funds, yet participation and consistency remain the weak points.
Why So Many People Fall Behind
The reasons are rarely a single bad decision. For today’s 50-year-olds, the prime saving years collided with the financial crisis, stagnant wages in many sectors, rising housing and health care costs, and the expense of raising children and, increasingly, supporting ageing parents at the same time.
Career interruptions matter too. Time out of the workforce, freelance work without an employer plan, or years spent paying down debt rather than investing all reduce the powerful early compounding that retirement advice assumes. A decade of missed contributions in a person’s thirties cannot be recreated, but its effect can still be partly offset.
Catch-Up Moves That Still Work After 50
The tax system in the United States explicitly recognises the problem. From age 50, workers can make additional catch-up contributions to 401(k) plans and individual retirement accounts above the standard limits. Maximising those allowances — even for the final 10 to 15 years of a career — can add a substantial sum, especially when employer matching is included. Claiming the full match remains, in effect, an immediate return that no market strategy can reliably beat.
Delaying Social Security is another powerful lever. Claiming later increases monthly benefits for life, which reduces pressure on savings in later years. For many households, working a few years longer, even part-time, helps twice: more time to save and fewer years of retirement to fund.
Spending review is less glamorous but equally effective. Redirecting money freed by a paid-off mortgage, refinancing remaining debt at lower cost, or trimming recurring subscriptions into retirement accounts turns existing cash flow into future security without requiring a dramatic lifestyle change.
Reframing the Target
Financial planners caution against treating a single magic number as pass or fail. Retirement readiness depends on expected spending, housing costs, health, other income such as pensions or rental property, and where someone plans to live. A household with a paid-off home and modest spending may need far less than a generic benchmark suggests, while a high-cost household may need more.
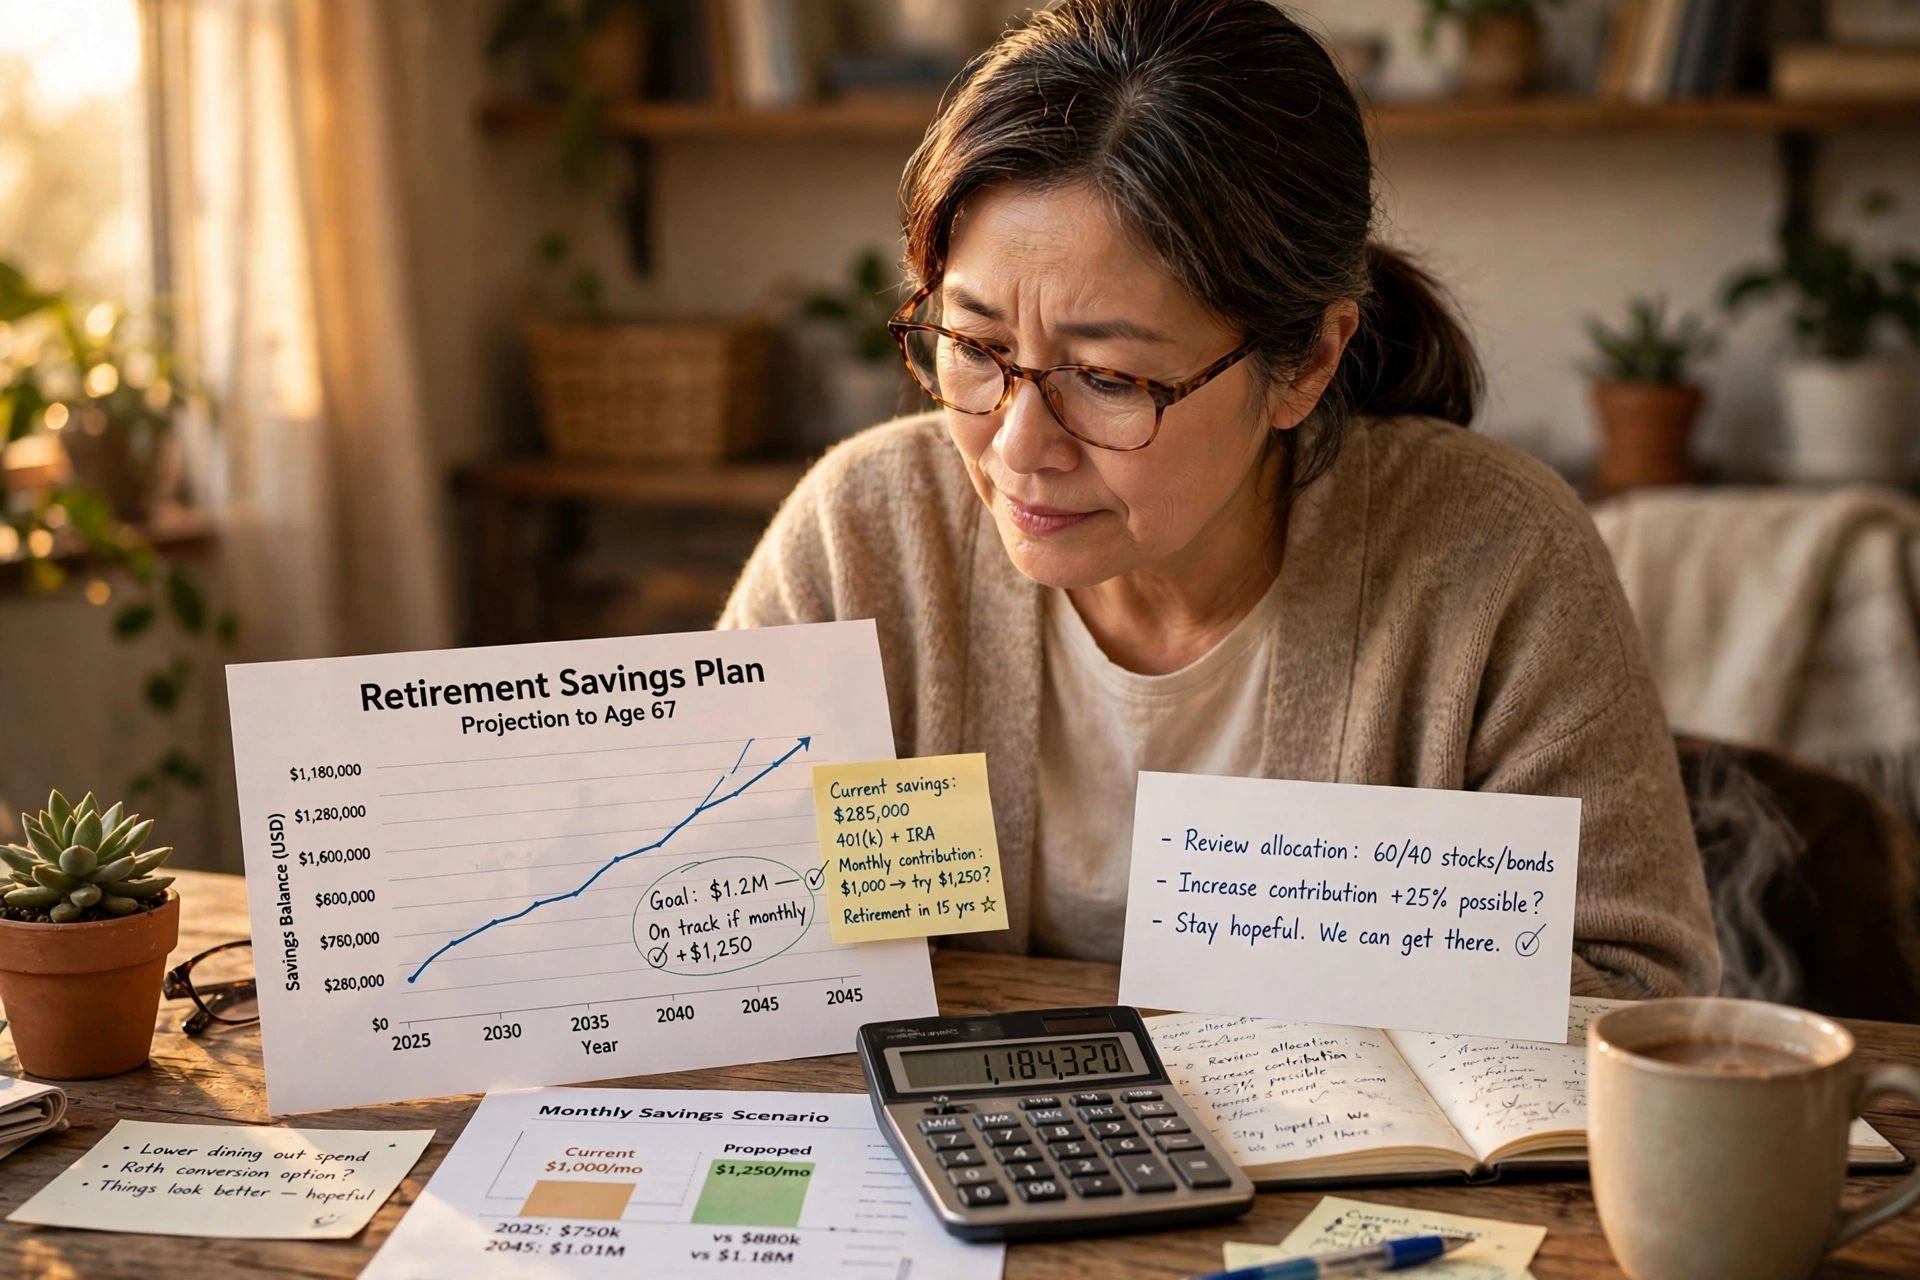
The discussion sparked by the new numbers is therefore useful not because it shames savers, but because it replaces vague fear with a measurable starting point. At 50, the most productive response is a clear inventory — current balances, expected Social Security, debts and monthly spending — followed by the few high-impact moves above, repeated consistently.
Fifteen years of focused saving, catch-up contributions and compounding will not rewrite the past, but for many Americans it is enough to move from anxious to adequately prepared. Being behind at 50 is common. Staying uninformed about it is the part that can still be fixed, starting now.